Foreclosure Auction Volume Increases 25% to New Post-Pandemic High in Q3 2026 Led by Sharp Increases in FHA-Insured and Recent-Vintage Loans
FHA foreclosure auction volume up 73% to highest level since Q1 2019, a 7.5-year high
October 22, 2026
KEY POINTS
- Completed foreclosure auctions at 70% of Q1 2020 levels; up 25% year over year — seventh consecutive annual increase.
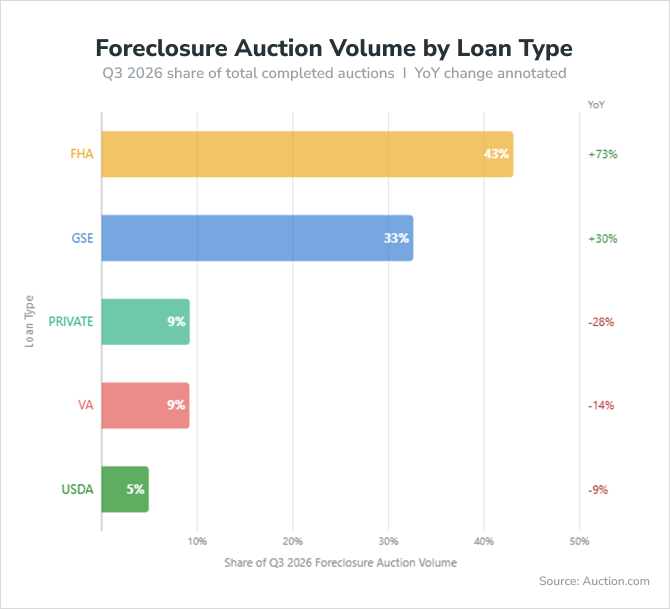
- FHA foreclosure auction volume up 73% year over year to highest level since Q1 2019, accounting for 43% of all foreclosure auction volume in Q3.
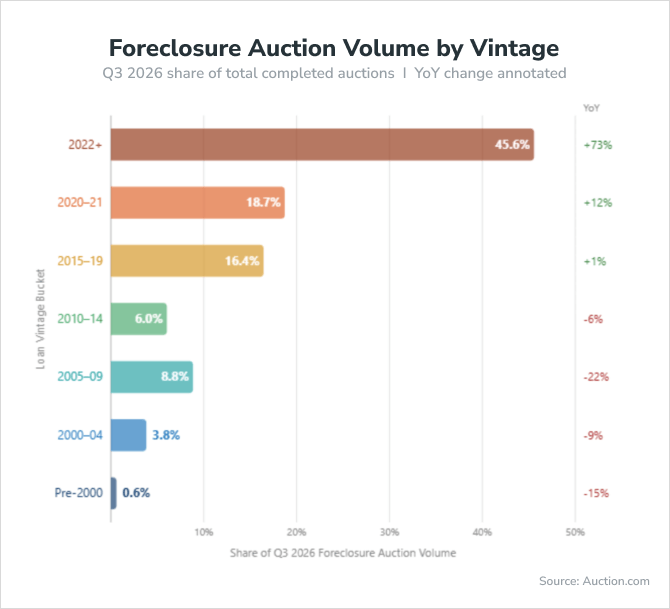
- 2022+ vintage volume also up 73% from a year ago, accounting for 46% of all foreclosure auction volume in Q3.
- REO auction volume up 18% from a year ago, at 51% of Q1 2020 levels.
- Pricing adjusts 3% lower for FHA volume, helping demand jump 19% from a year ago.
- REO auction demand spikes 29% from a year ago as auction pricing adjusts 3% lower.
OVERVIEW
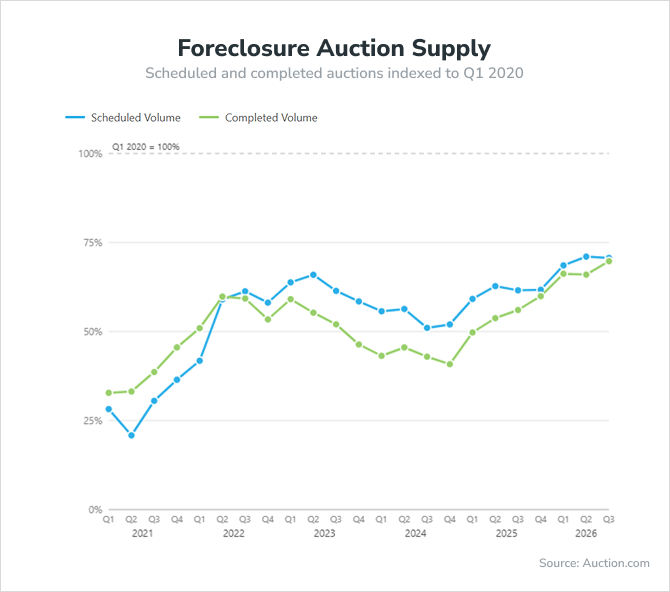
Foreclosure auction volume continued its upward trajectory in Q3 2026. Completed auctions rose 25 percent year over year, making Q3 2026 the seventh consecutive quarter of annual volume gains and the highest quarterly total since Q1 2020. Scheduled foreclosure auctions increased 15 percent from a year earlier, reaching 71 percent of the Q1 2020 level, a new post-pandemic high.
Loans insured by the Federal Housing Administration (FHA) accounted for the lion’s share of the increase. FHA foreclosure auction volume surged 73 percent year over year and, for the first time in this cycle, crossed its own pre-pandemic baseline, reaching 117 percent of Q1 2020 levels — the highest since Q1 2019. FHA-insured mortgages accounted for 43 percent of all foreclosure auction volume, the highest share since Q1 2015.
Mortgages originated in 2022 or later represented 46 percent of all foreclosure auction activity in Q3 2026, as an early wave of higher-rate post-pandemic originations continues moving through the default pipeline. Foreclosure auction volume for those recent-vintage loans increased 73 percent from a year ago.
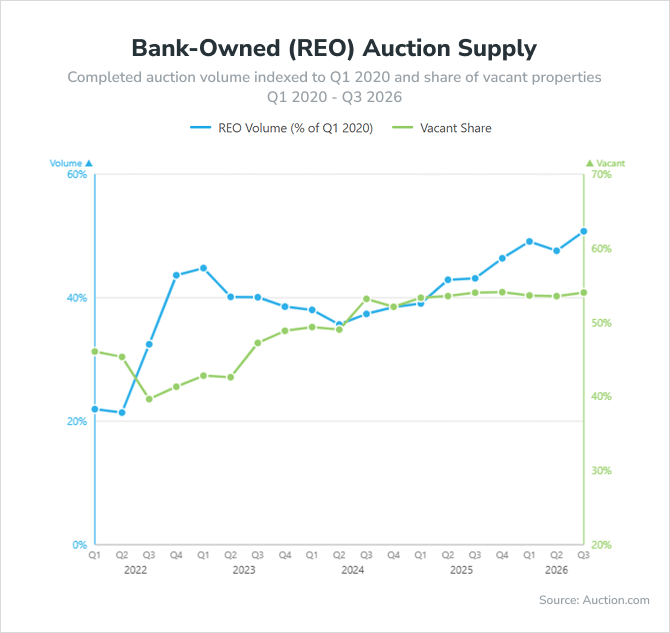
Auction volume for real estate owned (REO) properties in Q3 2026 increased 18 percent from a year ago — the seventh consecutive quarter with an annual increase — reaching the highest level since Q3 2020 and 51 percent of the pre-pandemic level in Q1 2020.
Scheduled foreclosure auction volume for the fourth quarter indicates both foreclosure auction volume and REO auction volume will continue to increase in that quarter. Compared to the same time last year, scheduled foreclosure auction volume is up 11 percent for October, up 31 percent for November, and up 15 percent for December.
DISTRESSED DEMAND
Foreclosure Auction Sales Rate
The foreclosure auction sales rate eased to 45.5 percent in Q3 2026, down 5 percent from Q2 2026 but essentially flat year over year (+0.4 percent) and still 8 percent above the Q1 2020 pre-pandemic benchmark — the seventh consecutive quarter the sales rate has exceeded that level.
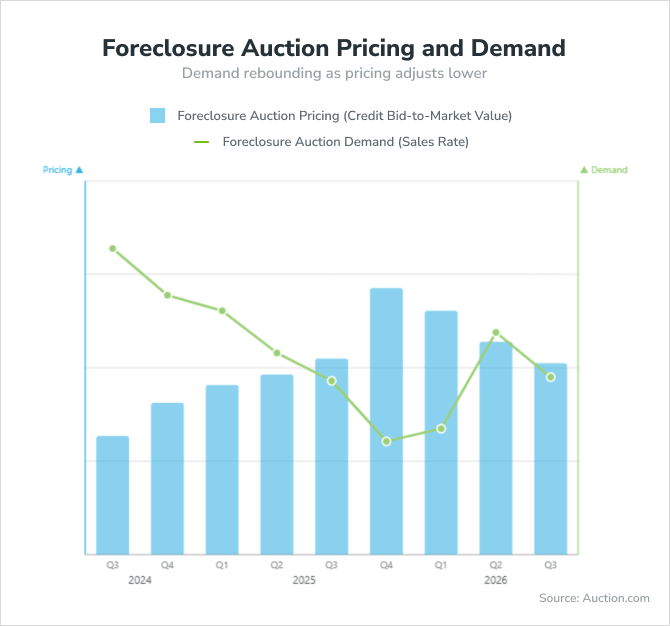
Conversely, demand jumped for FHA-insured foreclosure auction volume compared to a year ago as pricing adjusted lower for those assets. The FHA sales rate increased 19 percent from a year ago as pricing for those properties decreased 3 percent from a year ago. (More on pricing in the distressed pricing section below.)
REO Auction Sales Rate
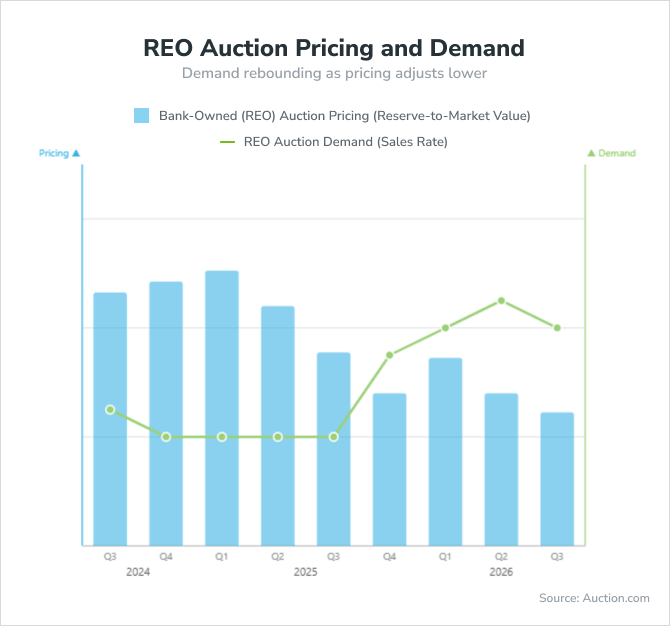
REO auction demand also improved substantially on a year-over-year basis as pricing adjusted lower. The sales rate for all REO auctions rose 29 percent from Q3 2025 as pricing adjusted 3 percent lower over the same period.
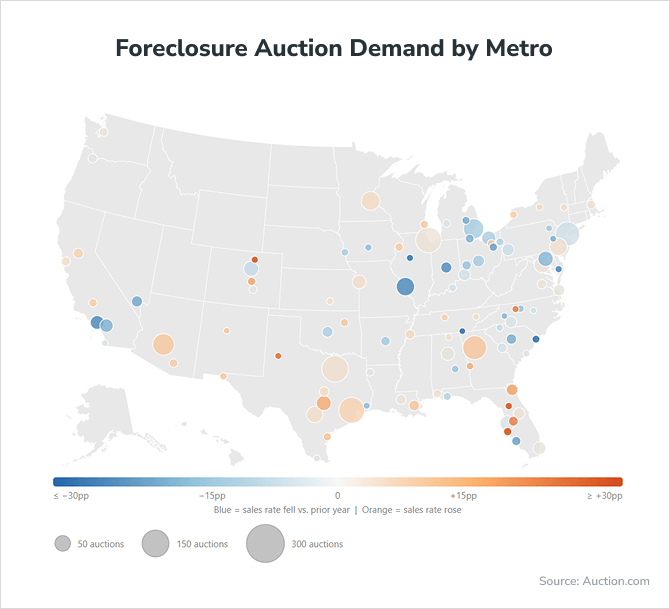
Foreclosure Auction Demand by Metro
Of 64 major markets tracked, exactly half (32) posted year-over-year sales rate gains and 32 declined. Demand held up best in Sun Belt and Midwest markets with healthy job growth, while the Great Lakes industrial corridor and several high-cost coastal markets showed continued softness.
Markets with the biggest year-over-year increase in sales rate were Ocala, Florida (up 553 percent), North Port-Sarasota-Bradenton, Florida (up 192 percent), Lafayette, Louisiana (up 125 percent), Lakeland, Florida (up 86 percent), and Colorado Springs, Colorado (up 45 percent).
Among markets with the most foreclosure auction volume in Q3 2026, those with an increasing sales rate included Houston, Texas (up 15 percent), Dallas, Texas (up 5 percent), Atlanta, Georgia (up 18 percent), Chicago, Illinois (up 3 percent), and Phoenix, Arizona (up 16 percent).
Among markets with the most foreclosure volume in Q3 2026, those with a decreasing sales rate compared to a year ago included New York, New York (down 10 percent), Detroit, Michigan (down 27 percent), St. Louis, Missouri (down 47 percent), Tampa, Florida (down 6 percent), and Riverside-San Bernardino, California (down 34 percent).
Buyer Price Demand
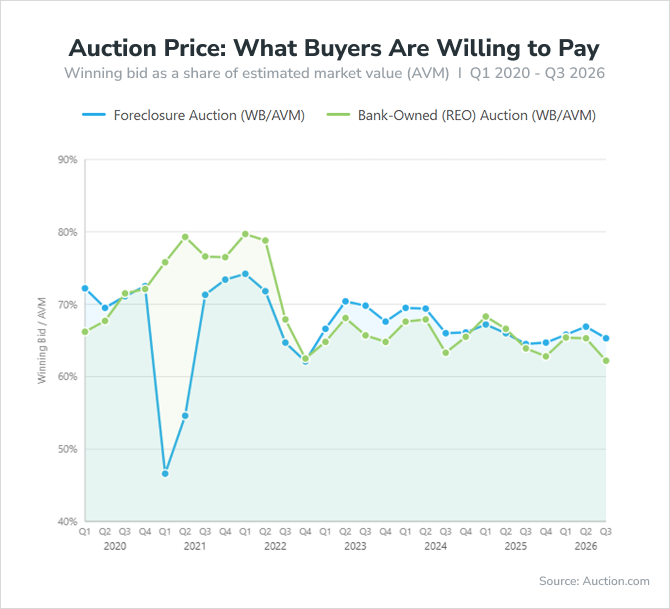
Foreclosure auction buyers paid an average of 65.3 percent of estimated retail market value in Q3 2026, down from 66.8 percent in Q2 2026 but up from 64.5 percent in Q3 2025. Buyer pricing remains within its recent range — roughly 92 percent of Q1 2020 benchmark levels — with the modest QoQ pullback consistent with seasonal demand softening.
Among the 64 major markets tracked in Q3 2026, 27 posted an annual increase in foreclosure auction price demand, led by Charlotte, North Carolina (up 36 percent), North Port-Sarasota-Bradenton, Florida (up 26 percent), Wichita, Kansas (up 21 percent), Akron, Ohio (up 16 percent), and Pensacola, Florida (up 14 percent).
The other 37 markets posted an annual decrease in foreclosure auction price demand in Q3 2026, led by Cape Coral-Fort Myers, Florida (down 17 percent), Toledo, Ohio (down 16 percent), Columbus, Ohio (down 15 percent), Shreveport, Louisiana (down 15 percent), and Little Rock, Arkansas (down 15 percent).
REO buyers paid an average of 62.2 percent of estimated retail market value, down from 65.2 percent in Q2 and 64.0 percent in Q3 2025, as growing REO inventory and lower auction pricing gave buyers the opportunity to land better deals.
DISTRESSED SUPPLY
Overall Volume
Completed foreclosure auctions in Q3 2026 were up 6 percent from Q2 and up 25 percent from Q3 2025. The scheduled pipeline of foreclosure auctions was essentially flat from Q2 but up 15 percent from a year ago, suggesting the completed volume tailwind has room to continue. Together, completed and scheduled foreclosure auction volume have now recorded annual gains for seven consecutive quarters.
REO auction volume in Q3 2026 rose 7 percent from Q2 and 18 percent from Q3 2025, marking seven consecutive annual increases. The share of vacant REO properties held nearly constant at 54.0 percent, in line with Q2 2026 (53.9 percent) and Q3 2025 (54.1 percent).
By Loan Type
FHA-insured mortgages drove the Q3 surge, rising 73 percent year over year to the highest level since Q1 2019, 17 percent above the pre-pandemic benchmark in Q1 2020. Foreclosure auction volume from the Government Sponsored Enterprises (GSEs) Fannie Mae and Freddie Mac grew at a more measured 30 percent on a year-over-year basis.
By Loan Vintage
Mortgages originated in 2022 or later accounted for 46 percent of all completed foreclosure auctions in Q3 2026, growing 73 percent year over year. This cohort — the first generation of borrowers who locked in at materially higher rates than their 2020 to 2021 counterparts — is arriving in the foreclosure auction market in increasing numbers.
Older vintages continued to contract. Great Recession-era loans (2005 to 2009) fell 22 percent year over year to less than 9 percent of volume. Pre-2015 originations collectively represent just 19 percent of activity.
By State
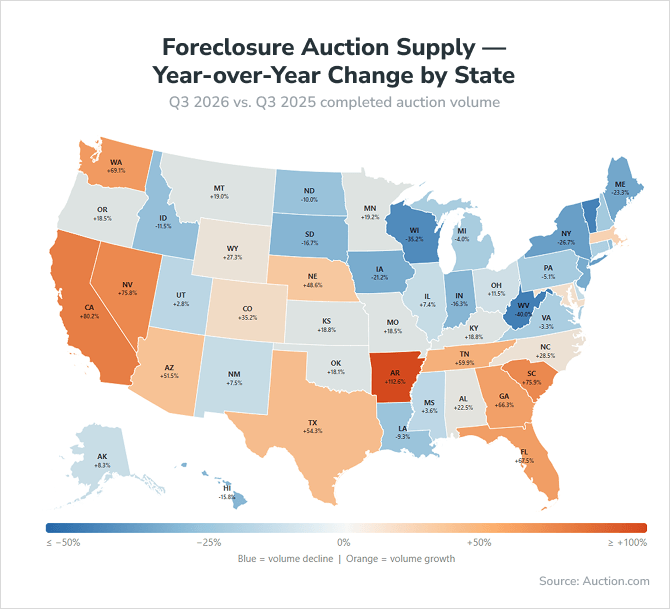
Thirty-one states recorded year-over-year increases in completed foreclosure auction volume in Q3 2026, including Texas (up 54 percent), Florida (up 67 percent), California (up 80 percent), Ohio (up 12 percent), and Illinois (up 7 percent).
States with the largest year-over-year percentage increase in foreclosure auction volume were Arkansas (up 113 percent), California (up 80 percent), South Carolina (up 76 percent), Nevada (up 76 percent), and Washington (up 69 percent).
Eighteen states reached or exceeded their Q1 2020 pre-pandemic baseline in the third quarter of 2026, including Texas (38 percent above Q1 2020 baseline), California (9 percent above), Arizona (31 percent above), Louisiana (41 percent above), and Colorado (246 percent above).
After Colorado, states with Q3 2026 foreclosure auction volume furthest above their Q1 2020 pre-pandemic benchmark were Connecticut (181 percent above), Utah (48 percent above), Wyoming (47 percent above), and Alaska (44 percent above).
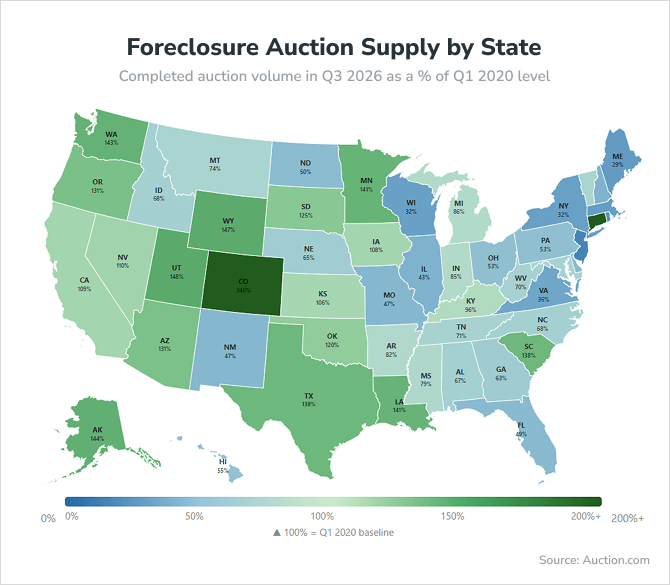
States with the most foreclosure auction volume in Q3 2026 were Texas (15 percent of national total), Florida (8 percent), California (6 percent), Ohio (5 percent), and Illinois (5 percent).
DISTRESSED PRICING
Foreclosure Auction Pricing
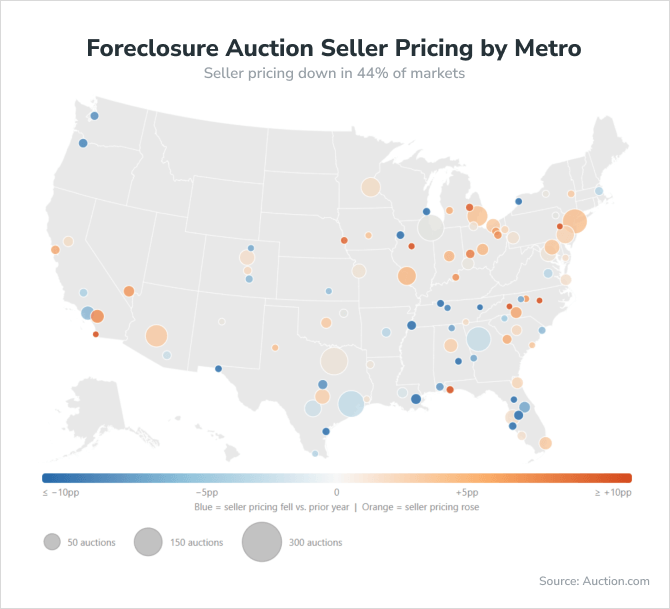
Foreclosure auction seller pricing — the minimum amount sellers are willing or able to take (credit bid) as a percentage of estimated market value — came in at 64.2 percent in Q3 2026, down from 65.1 percent in Q2 and essentially flat year over year (-0.3 percent).
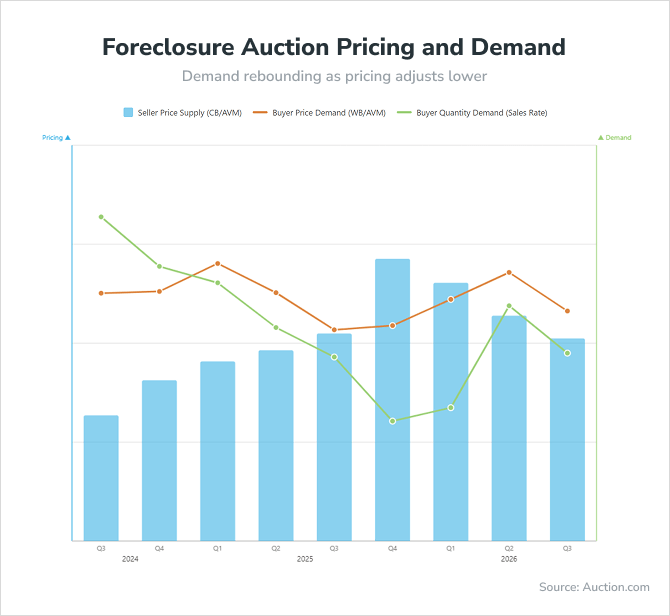
The relatively flat pricing overall masks divergent trends by loan type and vintage. By loan type, the lowest foreclosure auction pricing in the third quarter of 2026 was for loans insured by the U.S. Department of Agriculture (USDA) at a 55.9 percent credit bid-to-value ratio, followed by GSE-backed loans (62.1 percent), and FHA-insured loans (62.6 percent). The FHA pricing was down from 64.6 percent a year ago. Loans insured by the Department of Veterans Affairs (VA) had the highest pricing among loan types with a 76.3 percent credit bid-to-value ratio followed by privately held loans at 66.8 percent.
The lowest-priced vintage cohort was for loans originated between 2010 and 2014, with a 48.0 percent credit bid-to-value ratio on average, followed by pre-2000 (50.2 percent), and 2000 to 2004 (57.1 percent). The highest-priced vintage cohort was for loans originated in 2022 or after with a 70.5 percent credit bid-to-value ratio on average, followed by loans originated between 2020 and 2021 (64.4 percent), and loans originated between 2005 and 2009 (64.3 percent).
Year over year, credit bid-to-value ratios (seller pricing) declined in 25 of 64 metros, led by Ocala, Florida (down 22 percent), North Port-Sarasota-Bradenton, Florida (down 17 percent), New Orleans, Louisiana (down 15 percent), Memphis, Tennessee (down 15 percent), and Lakeland, Florida (down 14 percent).
Seller pricing (credit bid-to-value ratio) increased from a year ago in the remaining 39 markets analyzed, led by Raleigh, North Carolina (up 47 percent), Pensacola, Florida (up 25 percent), Canton, Ohio (up 14 percent), Dayton, Ohio (up 13 percent), and Akron, Ohio (up 11 percent).
REO Auction Pricing
REO reserve pricing fell to 74.9 percent of estimated market value, down from 75.6 percent in Q2 2026 and down from 77.1 percent in Q3 2025. The lower pricing for REO auctions compared to a year ago corresponded with a rise in sales from a year ago (see Demand Section above).
MACROECONOMIC TRENDS
Rate
Probability
Index
Sentiment Index
HOUSING & MORTGAGE TRENDS
Home Sales
Prices
Mortgage Rate
Mortgage Rate